
Listed company Checkit has ended a formal sale process initiated six months ago after failing to agree a take-private takeover.
The Cambridge firm had put itself up for sale amid frustration at its market cap valuation and the focus on ‘short-termism’ in public markets.
However it is now playing a more optimistic tune as it will remain a PLC for the foreseeable future.
An augmented workflow and smart sensor automation company for frontline workers, Checkit has been listed on the public markets since 1997 and its share price peaked at 64 pence in 2021.
Prior to the commencement of the formal sale process in March this year, it had been trading around 14p. News of the sale process saw it climb as high as 26p and remain in the 20s.
However this morning’s news has caused it to lose 27% of its valuation in early trading (with shares prices at 16.5p, writing at 9.30am).
Checkit said it had entered discussions with several parties and that its board had determined that it would not consider proposals below 30p per share.
It received non-binding offers from three credible potential acquirers following initial due diligence at 22p, 25p and a range of 31-33p per share.
“Following discussions with the first two parties, the board concluded that it was not possible to agree a valuation at a level which it considered it could recommend to shareholders, and those proposals did not progress,” it said.
“The third party subsequently decided not to proceed, having concluded that an acquisition of Checkit did not fit closely enough with its existing business.”
Verbal indications of interest from other credible potential acquirers in the range of 20-25p per share were not pursued, it said, while one verbal indication of 40p was not progressed by the party.
“The formal sale process has reinforced the board’s view that Checkit represents a strategically relevant platform within an attractive and consolidating market,” it stated this morning. “Checkit is now also operating from a substantially strengthened financial and strategic position.”
The firm also reported its results for the six months ended 31st July 2026 this morning.
Adjusted EBITDA from continuing operations improved by £1.2m to a profit of £300,000 (H1 FY26: £900,000 loss).
Recurring revenue from continuing operations increased by 4% to £6.1m and represented 97% of revenue (H1 FY26: £5.8m and 96%).
Last year Checkit’s bid to acquire fellow PLC Crimson Tide collapsed following a long-running all-share takeover saga. The required majority of shareholders in Checkit did not back the deal, with 51% voting in favour and 49% against.
Following the news, Checkit conducted a review of its operations and cost base. It settled upon a restructuring which resulted in a raft of redundancies and shaved £4m off its annual cost base.
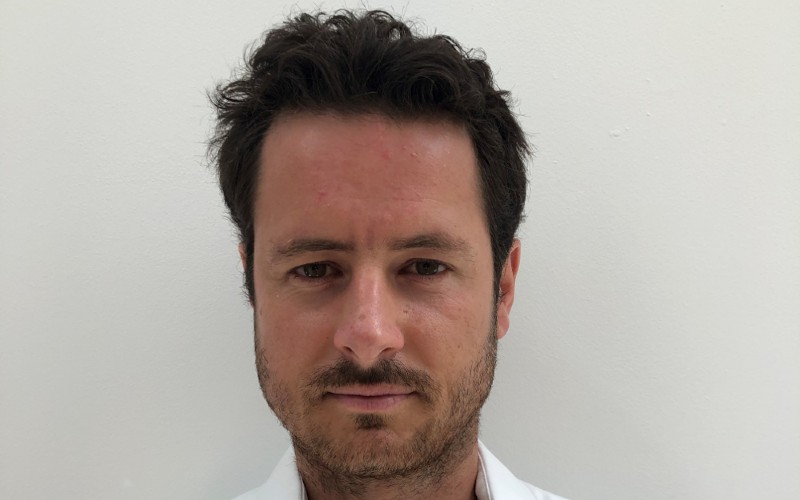
This morning CEO Kit Kyte (pictured) said: “H1 FY27 marks an important inflection point for Checkit, with the benefits of the transformation undertaken over the past year now clearly reflected in our financial performance. We have moved from funding significant new product development programmes to an EBITDA-profitable business with 97% recurring revenue and a materially lower cost base.
“Our task now is straightforward: deepen our position in medical, focus retail investment on high-quality multi-site opportunities, complete the move to one cloud platform and continue to improve commercial performance. These priorities underpin our two-year value-creation framework, which will guide how we invest and grow the business with financial discipline.
“We enter this next phase as a simplified business: with differentiated technology, mission-critical customer use cases, high recurring revenue and a cost base capable of producing meaningful operating leverage. We are confident in the opportunities ahead.”
Online retailer ‘shut down’ with £6.3m unexplained transactions